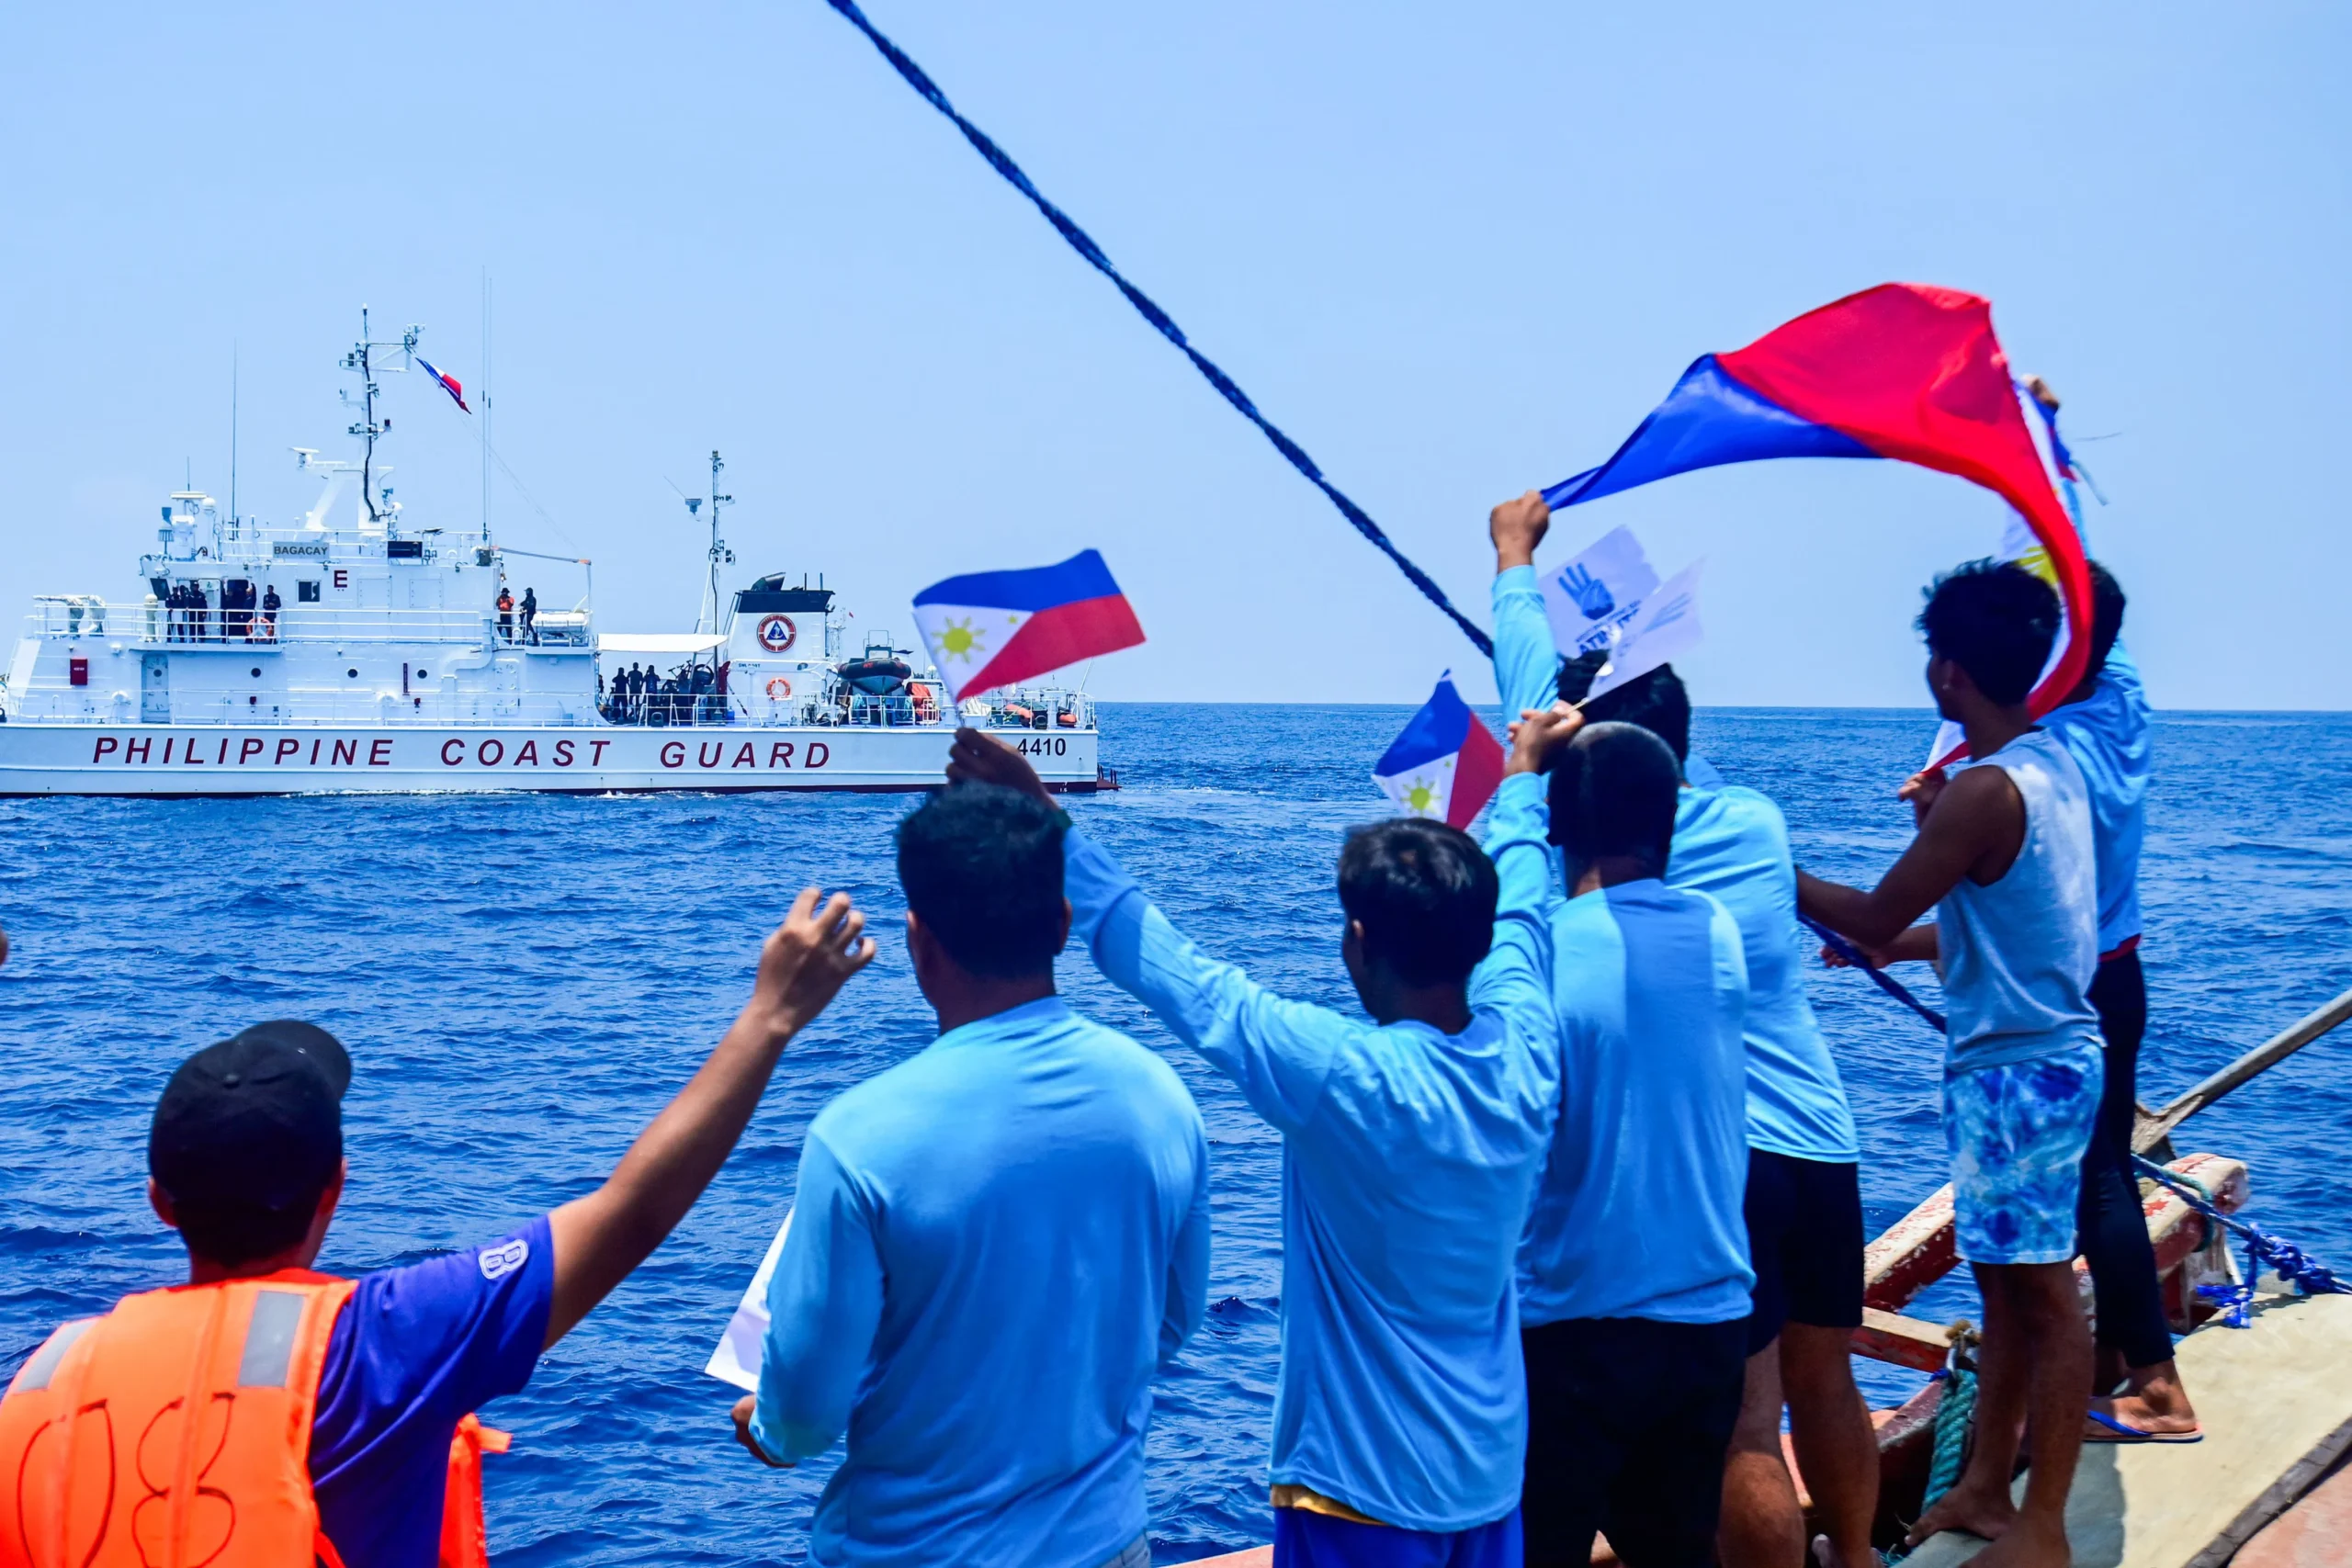
Escalating maritime disputes across the West Philippine Sea are forcing Southeast Asia's travel industry to recalibrate, with a pronounced shift toward inland and mainland itineraries. While localized skirmishes directly disrupt high-potential marine and expeditionary voyages, the broader regional sector is adapting to changing traveler demographics, rising logistics costs, and a faster-than-expected transition away from coastal routes.
Industry leaders stress that the regional travel narrative is not defined by naval posturing. Instead, the friction serves as a reminder of a core hospitality principle: agility, demographic diversification, and authentic product evolution remain the most effective counters to geopolitical headwinds.
Luxury expedition operators face a frozen frontier
For luxury expedition operators, the stakes are intensely commercial. The biodiversity-rich waters of the disputed corridor hold unmatched potential for premium diving, liveaboard cruising, and conservation-led marine expeditions. Yet persistent gray-zone tactics and sovereign posturing have effectively halted civilian infrastructure development for protection and conservation.
Bold initiatives like the Philippines' Great Kalayaan Expedition and Malaysia's curated dive operations off Layang Layang illustrate what could be achieved under stable conditions. However, major international cruise lines continue to give these sectors a wide berth. With foreign ministries issuing cautious advisories, underwriters deem disputed corridors commercially uninsurable, keeping luxury marine exploration tethered to familiar shorelines.
This dynamic is particularly acute for operators like Ponant and Silversea, which have scaled back planned itineraries through the Spratlys, redirecting vessels toward Indonesia's Raja Ampat or the Philippines' Palawan instead. The result is a concentration of demand in safer, well-established marine destinations, while the frontier remains untapped.
Outbound flows and the China factor
The volatility also reverberates through outbound dynamics, especially as China has long been a cornerstone of visitor volume and spending across the region. As maritime posturing spills into nationalist discourse, arrivals to vocal claimant states experience swift disruptions. When travel sentiment cools, hoteliers, regional transport providers, and tour operators in direct claimant nations must scramble to backfill occupancy.
Meanwhile, diplomatically insulated, non-claimant destinations within the Association of Southeast Asian Nations (ASEAN) frequently absorb this redirected footprint. Thailand, Vietnam, and Indonesia are already seeing increased bookings from Chinese and Western travelers seeking friction-free getaways. For instance, Bangkok's luxury hotel segment has reported a 15% uptick in forward bookings from Chinese groups, while Bali's villa market remains robust.
Operational pressures mount
Beyond direct guest flows, the background operational machinery faces sustained pressure. The contested waterways are among the planet's busiest maritime arteries, and heightened military readiness inflates aviation fuel expenditures, pushing domestic flight fares higher and stretching operating margins for regional ferry networks. Airlines like Cebu Pacific and AirAsia have noted fuel cost increases of 8-12% on regional routes, which are being passed on to consumers.
Compounding this strain, coastal community disruption has triggered an unexpected labor migration. As artisanal fishing grounds face operational restrictions, displaced maritime workers naturally transition toward terrestrial tourism services. This influx risks saturating localized service sectors, triggering fresh competition over municipal resources and coastal real estate. In the Philippines, for example, former fishermen are increasingly seeking roles in hospitality, putting downward pressure on wages in tourist hubs like Boracay and El Nido.
A resilient region, not a vulnerable one
However, characterizing regional tourism as fundamentally vulnerable misreads Southeast Asia's structural tenacity. The ASEAN Blue Economy Framework, which emphasizes sustainable marine resource management, provides a foundation for long-term resilience. Moreover, the region's pivot inland is not merely a defensive reaction but an opportunity to diversify product offerings.
Destinations like Chiang Mai, Luang Prabang, and Siem Reap are already benefiting from increased interest in cultural and heritage tourism. Hotel groups are responding: Clinique La Prairie's upcoming Phuket wellness resort signals a broader move toward health-focused inland retreats, while Jin Jiang Hotels' Renjoy debut in Desaru taps into Malaysia's underdeveloped eastern coast.
Travel advisors are also adapting, with many now promoting overland journeys that link multiple ASEAN countries, reducing reliance on any single coastal hub. This trend aligns with the shared ground planning initiatives reshaping regional tourism development, which emphasize coordinated infrastructure and cross-border itineraries.
For hoteliers, the key is rate discipline. As Philippine hotels lean on rate discipline to compete with regional rivals, the broader lesson is clear: in a volatile geopolitical climate, operational flexibility and product innovation are more valuable than ever.
The region's travel industry is not being derailed by naval posturing. Instead, it is demonstrating the agility that has long defined Southeast Asia's tourism success—pivoting inland, diversifying source markets, and investing in authentic experiences that transcend geopolitical friction.