Across the Asia-Pacific region and beyond, persistent inflation and macroeconomic uncertainty continue to weigh on consumer confidence. Yet the travel industry is witnessing a counterintuitive trend: experiential and immersive travel is not just holding its own but is actively outperforming the broader market recovery.
Consumer intelligence from major source markets indicates that international travel remains the top discretionary priority globally. What has changed is not the desire to travel but the methodology of spend. Rather than cancelling trips, travellers are deploying a strategy of financial reallocation to protect the core of their journeys.
As one industry expert puts it: “They are willing to compromise on short-haul flights, trim a night or two from an itinerary, or swap a five-star international chain for a boutique guesthouse, provided the savings directly fund hyper-local cultural immersion and genuine community engagements.”
The great divergence in travel demand
This behavioural shift has created a clear split in market dynamics. At the upper end, ultra-high-net-worth travellers continue to invest in bespoke, regenerative wellness retreats and conservation-focused private expeditions. Meanwhile, budget-conscious voyagers are leveraging regional connectivity to pursue rich, analog escapism closer to home.
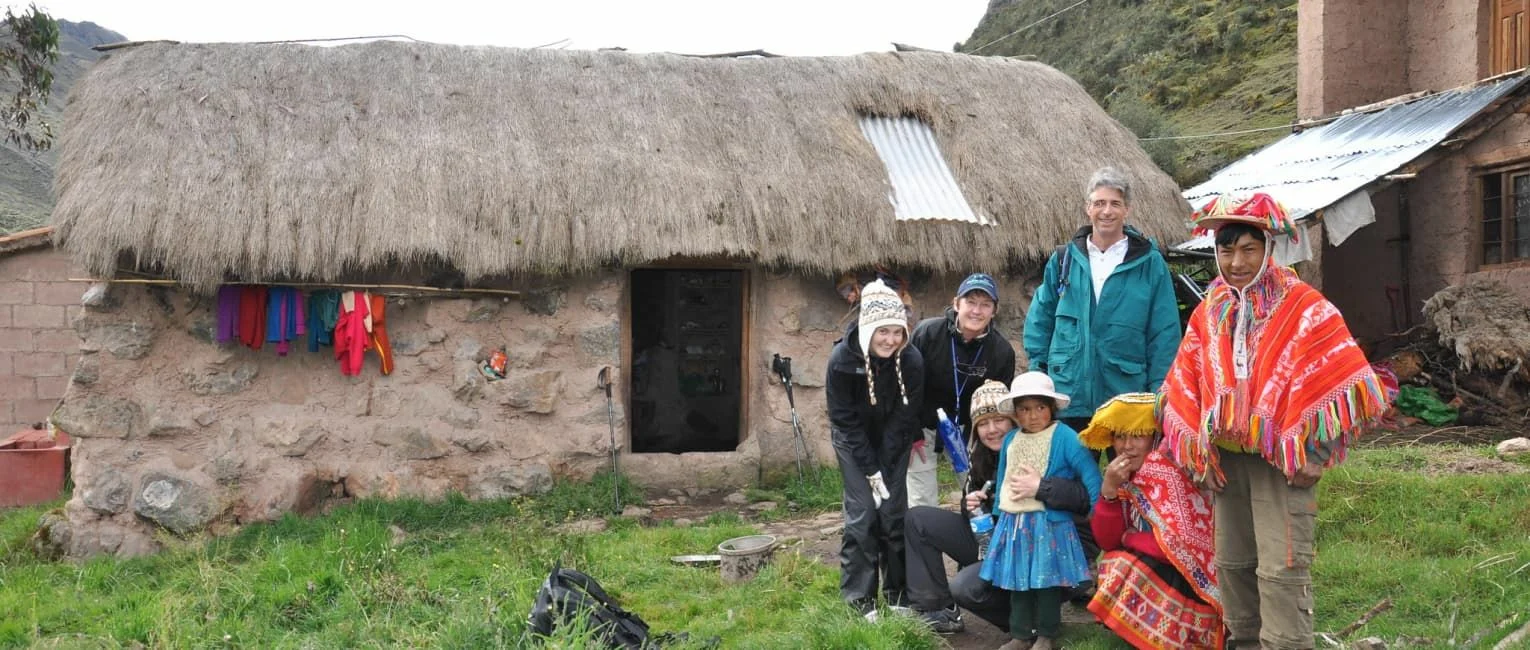
Driven by what some analysts call the ‘Endorphin Economy’, travel decisions are increasingly anchored around singular, memorable touchpoints rather than generic sightseeing checklists. This is evident in the rising popularity of culinary tours in Bangkok’s backstreets, homestays in Vietnam’s Mekong Delta, and community-based trekking in Nepal’s Annapurna region.
The structural shift exposes the widening chasm between conventional mass tourism and immersive exploration. Legacy models reliant on standard cruise departures, over-touristed heritage landmarks, and generic resort packages face mounting vulnerability to price saturation and local community pushback. In contrast, immersive tourism channels capital directly into emerging destinations and localised models, exhibiting exceptional resilience against inflationary shocks.
Analysts project the experiential segment will expand at a compound annual growth rate of 10.1 percent over the next decade, far outpacing the overall travel sector. This growth is supported by a broader trend toward shared ground planning in Southeast Asia, which prioritises community involvement and sustainable development.
With the broader travel sector projected to contribute a record US$12 trillion to global economic output, the secular appetite for discovery remains indisputable. However, sustaining this momentum amid persistent fiscal volatility requires a decisive shift toward low-carbon, community-first frameworks.
Forward-looking operators are already adapting. For example, Accor’s Greater China CEO emphasises knowing local consumers as key to winning the next chapter. Similarly, Accor Plus research has reshaped its loyalty programme to reward experiential benefits over traditional perks.
By decentralising visitor footfall and prioritising genuine local partnerships, operators can insulate their bottom lines while delivering the profound sense of place modern travellers refuse to sacrifice. This approach aligns with Helsinki’s winter light art, which has reshaped urban tourism by turning public spaces into immersive attractions.
For travel professionals, the message is clear: the future belongs to those who can curate authentic, immersive experiences that resonate with the endorphin-driven traveller. Whether through boutique accommodations, community-based tours, or regenerative wellness retreats, the opportunity is vast—but only for those willing to evolve.